Choose the possibility
Explore the location, layout and plot. Think about the everyday things: the school run, space to work, where the pushchair goes and your first cup of tea in the garden.
Your new chapter can start before your new home is finished. Discover what it means to buy off plan, how to picture the possibilities and what to expect along the way.
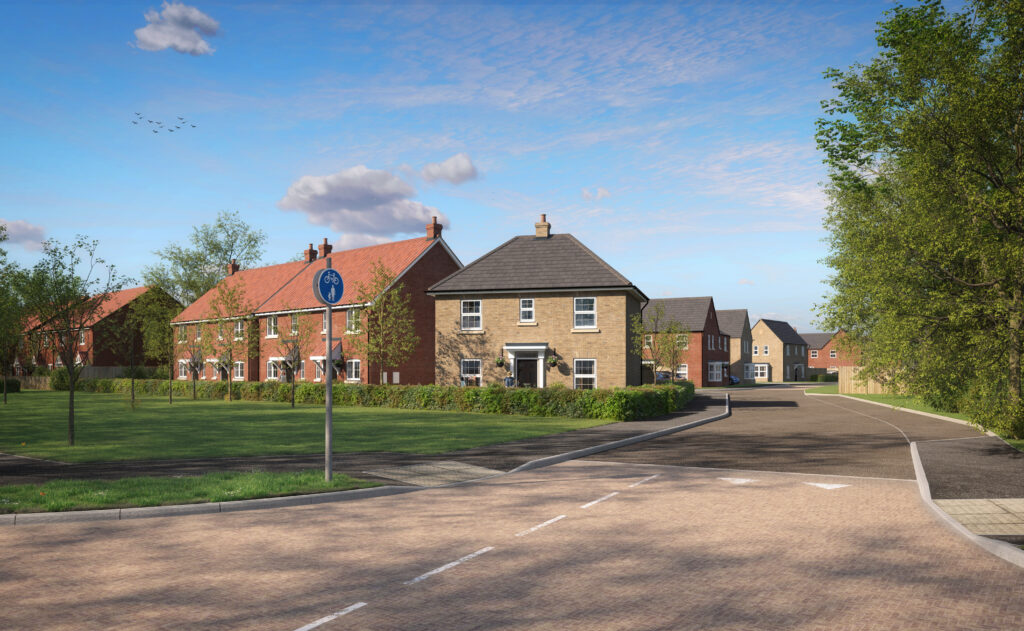
Buying off plan means choosing and progressing the purchase of a new home before it is finished. You use the plans, specification and information about your particular plot to decide whether it is right for you.
The home might be at an early construction stage, or it could already have walls and a roof. You may reserve it, and sometimes exchange contracts, before you can walk around the finished rooms. You move in after the home is ready and the legal purchase completes.
Off plan describes when you buy. Shared Ownership describes how you buy. You can buy an eligible share of a home that is still being built, then pay rent on the share you do not own. You live in the whole home.
Explore the location, layout and plot. Think about the everyday things: the school run, space to work, where the pushchair goes and your first cup of tea in the garden.
Look beyond a lovely image. Read the room dimensions, check what is included and get clear answers about costs, timescales and anything that matters to you.
Keep in touch as construction progresses. Your buying process and the building work can run alongside each other, with your solicitor and adviser helping you prepare.
A floor plan is your first walk through the home. Explore The Heron at Dunham View, Little Downham — a four-bedroom home at Plot 1 — then use the same questions when you look at your own home.
4.63m × 4.06m
The published floor plan for The Heron, Plot 1 at Dunham View. Dimensions are for guidance and may change; check the current details for your home before ordering furniture or fittings.
Compare room sizes with a space you already know. A maximum dimension may include an alcove; ask for the usable dimensions and check ceiling slopes, door openings and circulation space.
Check the garden direction, boundary, parking and neighbouring homes. Ask about footpaths, bin stores, shared access and any later building phases around your plot.
The same house type may have a mirrored layout or a different external finish. Ask for the current plan and specification for your plot number, including any changes since the brochure.
Ask which of these are available for the development you are interested in. Each tells you something different.
Understand how rooms connect and where your home sits in the development. Check your garden, parking space and access route as carefully as the inside.
“Can you talk me through this exact plot?”
Computer-generated images help you imagine the finished setting. Photos or 3D tours may show a similar home.
“Which details will be different in my home?”
We'll invite you to view your reserved home when it's ready.
“What can I visit now, and what can I see later?”
Building and buying do not always move in a straight line. Select a step to see what happens, who helps and what to ask.
You may be able to choose from homes released before they are complete. Availability changes, so ask what is actually released for sale.
Explore the neighbourhood, plan how you will use the rooms and organise your move while the building work progresses.
A new home gives you the opportunity to make a place your own. Check the specification so you know what will be ready and what you will need to buy.
You might not be able to view your exact home before reserving or exchanging. Ask for the evidence you need to feel informed.
Construction forecasts are estimates. Consider where you would live, and the extra costs, if the home is ready earlier or later than expected.
Keep copies of agreed plans and inclusions. Ask your solicitor how the contract deals with changes, delays and deposit protection.
A reservation fee holds a home for an agreed period, subject to the reservation terms. Confirm the current amount, when the reservation ends and the refund conditions. Do not assume an offer on another plot applies to yours.
Your mortgage deposit is your own contribution towards the share you buy. Your solicitor will explain the amount required at exchange and how it is accounted for at completion. It is separate from legal, mortgage and moving costs.
Ask for a full list of legal fees, searches and mortgage or valuation fees. Your solicitor can explain whether Stamp Duty Land Tax applies and how the Shared Ownership rules affect your options.
Allow for removals, furnishings and any overlap with your current home. Keep a contingency for a change in timing. The Key Information Document is the place to check the plot’s purchase costs, rent and charges before you reserve.
Your home may be repossessed if you do not keep up repayments on your mortgage or rent.
“Expected in autumn” helps you plan. It is not the same as a confirmed completion date. Ask how updates will be shared and keep your solicitor and mortgage adviser informed.
The current estimate of when the home will be ready. Weather, supply and checks can affect progress.
Some off-plan contracts use completion on notice. Your solicitor explains the trigger and how much time you have.
The purchase completes, funds are transferred and the keys can be released as arranged.
Use these prompts with the sales team, your solicitor and your mortgage adviser. Tick an item when you have an answer you understand.
Your ticks are saved in this browser on this device.
Not necessarily. It means the home is not yet finished when you begin the purchase. It might be at the foundations stage, have its main structure in place or be waiting for the final fit-out. Ask for the current build stage and the most recent estimate of when it will be ready.
Yes. Once we’ve released the price information for your chosen home, you can pay your reservation fee and reserve it.
Our homes come with pre-selected kitchens, flooring and tiles. We’re unable to offer changes or upgrades.
Treat it as a visual guide. Landscaping, furniture and surrounding buildings may be illustrative, and the image could show a different plot or a future phase. Ask how the image relates to your home. Use the agreed plans and written specification, with your solicitor’s advice, to understand what you are buying.
Your property purchase becomes legally binding when contracts are exchanged. A reservation has its own terms but is not the same as exchange. Your solicitor should explain the commitment, deposit arrangements and consequences of withdrawing before you exchange. We’ll refund your reservation fee if you withdraw before exchange, less any costs we’ve incurred.
If you withdraw before exchange, we’ll refund your reservation fee, less any costs we’ve incurred. After exchange, you are legally committed and withdrawing can have significant financial consequences. Your solicitor can explain what this means for your purchase.
Tell the sales team, your mortgage adviser and your solicitor. A lower valuation may affect the amount a lender will offer and whether the purchase can proceed on the planned basis. Do not assume a price change, extra borrowing or a different deposit will automatically resolve it; get advice before committing.
Not always. Your home may be ready while work continues on other plots, roads or landscaping. Ask what will be complete at handover, what is planned for later, how safe access will work and who will manage shared areas.
Explore our homes or talk to the Homemade Homes team about the developments you like. We can help you find the right information to take your next step.
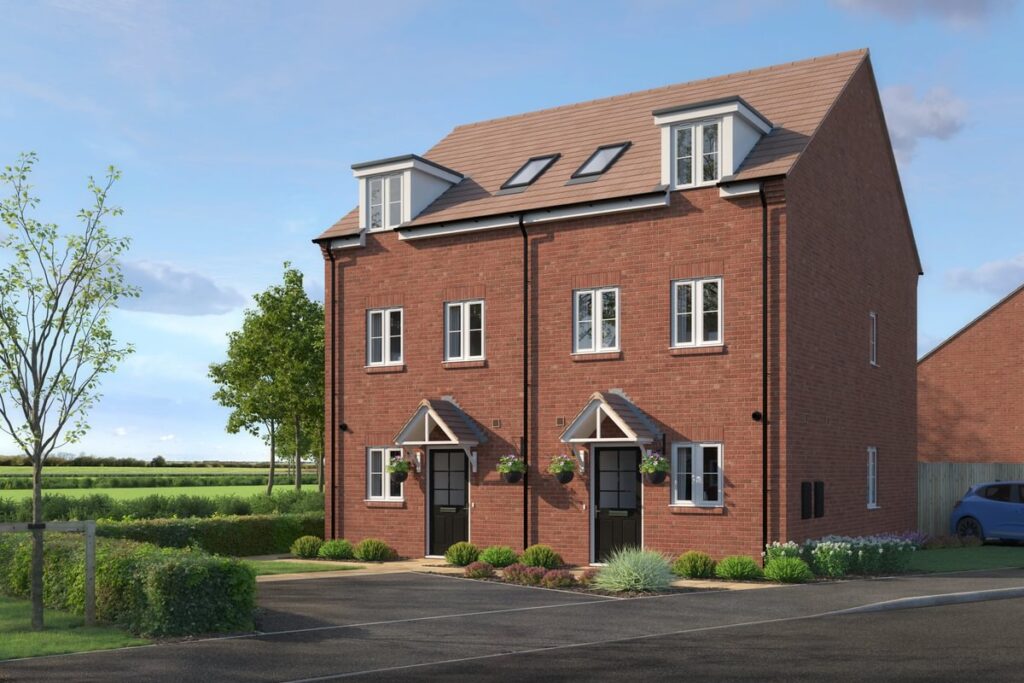
Upwell Meadows · Computer-generated image for illustration.
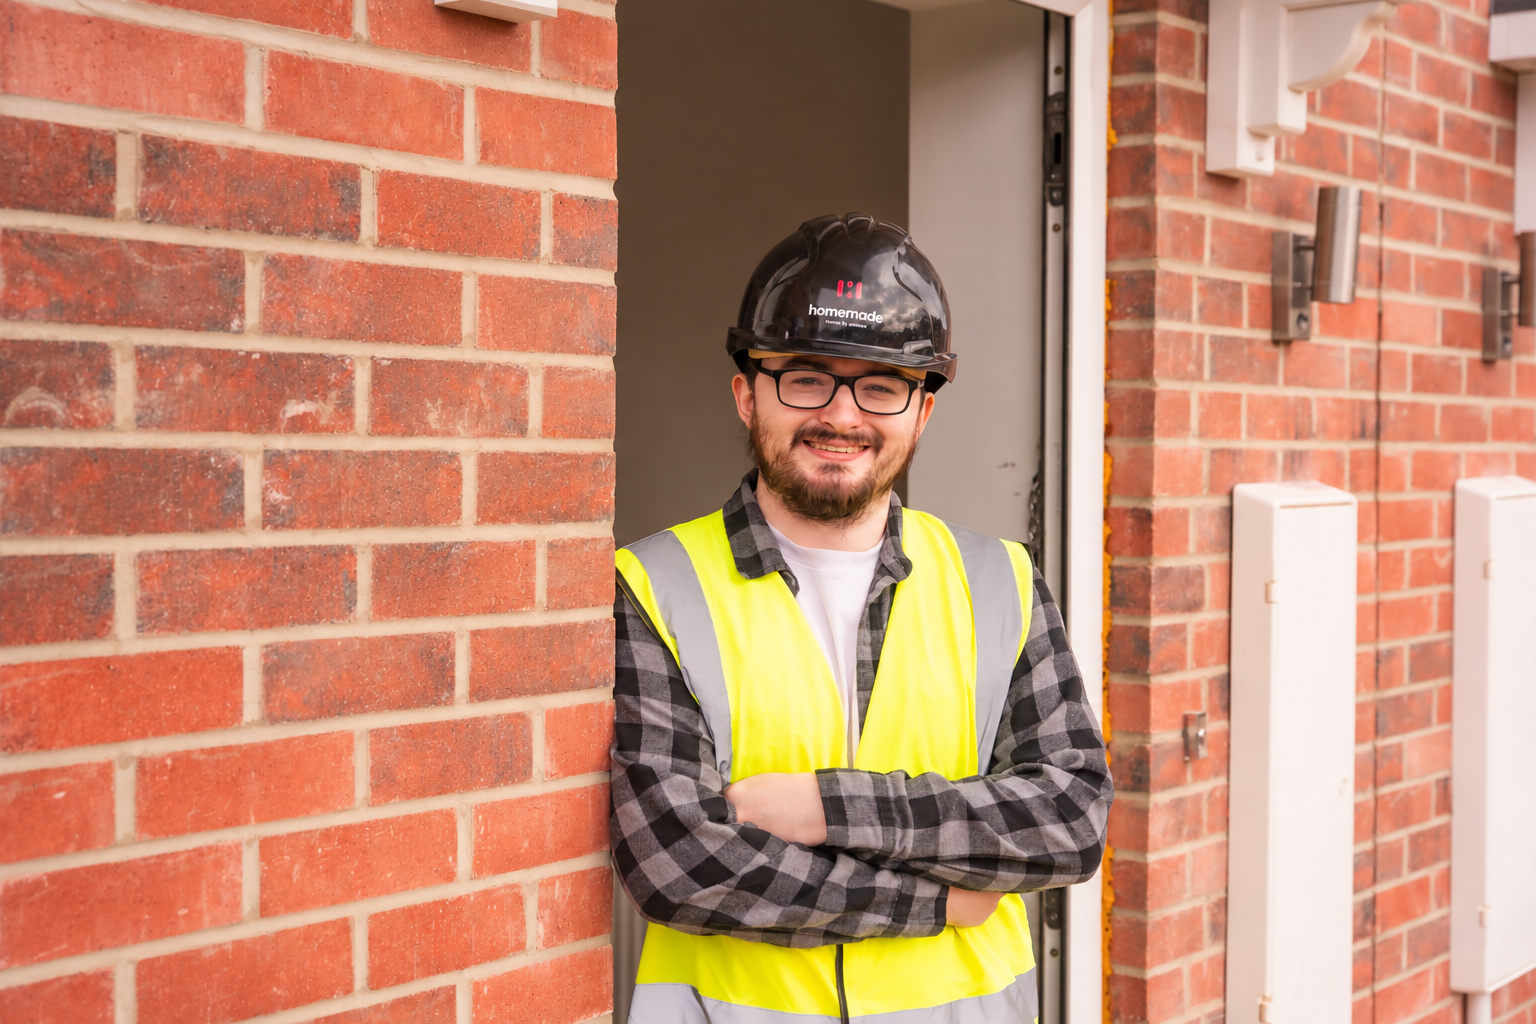
Ready to move out of his parents’ house, Ryan chose Shared Ownership at Monks Meadow in Spalding. He reserved his home while it was still being built, before he could view it in person.
Ryan felt nervous at first, but the team’s openness and support helped him feel more confident and focus on preparing for his move. When he finally stepped inside, the home he had imagined from the plans exceeded his expectations.
Read Ryan’s full story“It was better than I could have hoped.”
Ryan, Homemade Homes customer